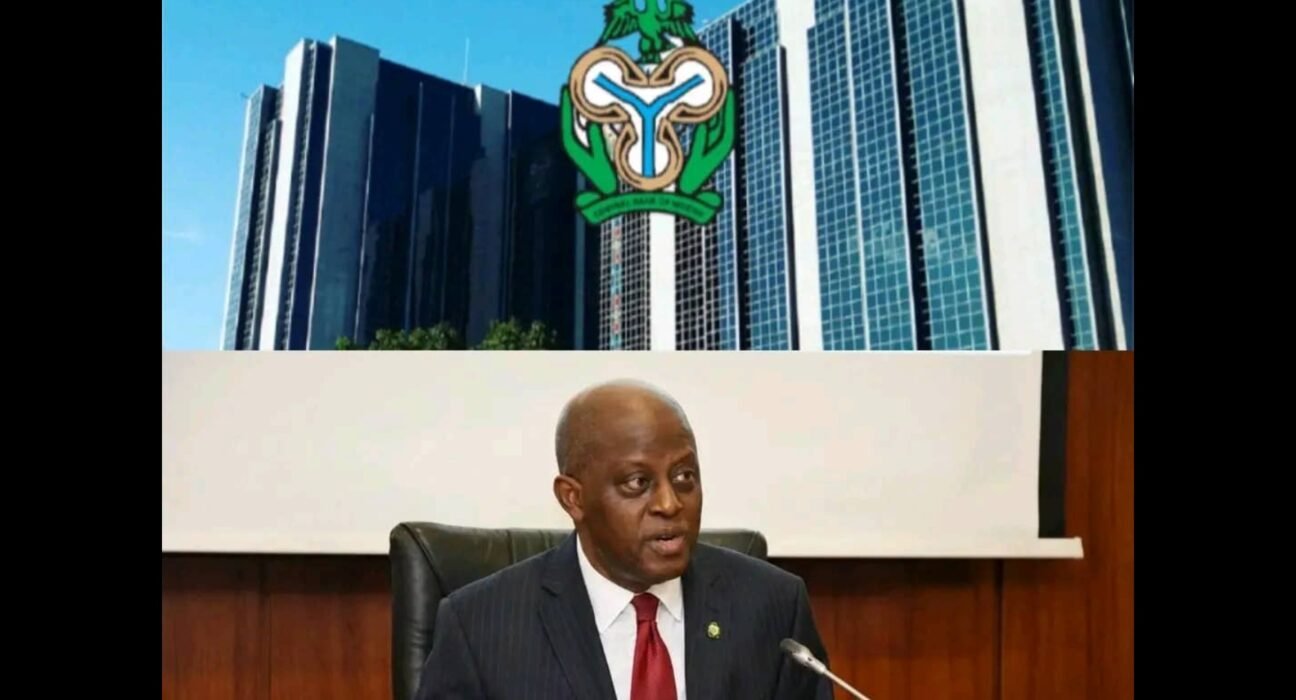
Nigeria’s foreign exchange reserves have recorded a fresh decline of about $300 million in just ten days, a development that has put the ongoing reforms of the Central Bank of Nigeria, CBN, under renewed scrutiny and raised concerns over the stability of the naira and the strength of the nation’s external buffers.
According to official data released by the apex bank, the country’s external reserves, which had risen to $55.17 billion on November 2, 2026, dropped to $54.87 billion on November 12, 2026, indicating a steady depletion of the foreign currency stockpile that the CBN relies on to intervene in the forex market and meet external obligations.
The figures represent a 0.54 per cent decrease in the country’s external reserves within a short period of ten days, a situation that has triggered anxiety among economists, investors, manufacturers and financial market operators who had expected the reserves to continue its upward trajectory following months of steady accretion.
Analysts said the downward movement in the reserves is a clear indication that the country’s external sector remains fragile and vulnerable to shocks, with serious consequences for the ability of the CBN to defend the naira, finance importation of critical goods, service foreign debts and maintain confidence in the Nigerian economy.
The latest decline shows that Nigeria’s external reserves have remained under sustained pressure despite aggressive efforts by the Central Bank under the leadership of Governor Olayemi Cardoso to reform the foreign exchange market, unify exchange rates, restore transparency, clear outstanding obligations and rebuild investor confidence in the Nigerian economy.
It will be recalled that the CBN in the last 24 months has introduced a series of far-reaching policy reforms, including the abolition of the multiple exchange rate regime, floating of the naira under a willing-buyer, willing-seller arrangement, clearing of over seven billion dollars in verified forex backlogs, and tightening of monetary policy to attract foreign inflows.
However, the recent fall in reserves suggests that underlying structural weaknesses in the economy, including low crude oil production that has consistently fallen short of Nigeria’s OPEC quota, volatility in global oil prices, rising import bills, heavy debt service payments and frequent interventions by the CBN, have continued to erode the gains of the reforms.
At the foreign exchange market, the naira also reflected the prevailing pressure as it closed on Friday at N1,353.10 per dollar at the official Nigerian Foreign Exchange Market, NFEM, while at the parallel market, also known as black market, it exchanged at an average of N1,430 per dollar, indicating a widening spread between the official and unofficial markets.
Forex dealers and Bureaux De Change operators attributed the pressure on the local currency to increased demand for dollars by different segments of the economy, including importers preparing for Christmas sales, manufacturers sourcing raw materials, parents paying tuition fees for children studying abroad, and individuals travelling for business and medical purposes.
The depletion of external reserves implies a reduction in the country’s financial safety net which is used to support international trade transactions, meet foreign payment obligations such as import bills and letters of credit, stabilise the exchange rate through market interventions and provide a buffer against external economic shocks.
Financial analysts who spoke on the issue said that although a $300 million decline may seem relatively small compared to the total reserves of over $54 billion, the speed at which the depletion occurred within ten days is concerning, especially coming after the CBN had celebrated the reserves hitting its highest level in over six years.
They pointed out that the reserves had only recently reached $55.17 billion in early November, the highest since 2019 when Nigeria enjoyed higher crude oil prices and production levels, a milestone that was widely reported as proof that the CBN’s reforms were delivering results and restoring stability to the forex market.
It is also important to recall that barely six days ago, official data showed that the external reserves had already dropped by about $90 million in just five days, confirming that the current decline is not an isolated occurrence but part of a consistent downward trend that has seen the country lose close to $400 million in less than two weeks.
The Central Bank has consistently maintained that movements in external reserves are normal under the current managed float exchange rate system and that its interventions in the forex market are part of its core mandate to ensure price stability, exchange rate stability and overall financial system stability.
The apex bank has also explained in previous communications that part of the reserves decline can be traced to routine international payment obligations, including servicing of external debts owed to multilateral creditors, payments for importation of petroleum products and other critical goods, and settlement of maturing foreign exchange contracts.
Meanwhile, market attention is now shifting to the upcoming 308th meeting of the Monetary Policy Committee, MPC, of the CBN scheduled for November 23 and 24, 2026, in Abuja, where key decisions are expected that could shape the direction of foreign reserves, exchange rate, inflation and broader economic outlook in the coming months.
The MPC, which is the highest monetary policy-making body of the CBN, is expected to carry out a thorough assessment of recent developments in both the global and domestic economy, including trends in inflation, economic growth, exchange rate, money supply, credit to the private sector, fiscal operations and external reserves before deciding on policy adjustments.
Economic analysts are divided on the likely outcome of the meeting, with some forecasting that the committee will keep all policy parameters unchanged, including the Monetary Policy Rate, MPR, Cash Reserve Ratio, CRR, and Liquidity Ratio, to allow the impact of previous rate hikes to fully manifest in the economy.
Others, however, believe that the committee may opt for further tightening of monetary policy to address lingering inflationary pressures, attract more foreign capital inflows, boost external reserves and provide additional support for the naira which has been under pressure in recent weeks.
Stakeholders have called on the Federal Government to intensify efforts to increase crude oil production to at least 2 million barrels per day, curb crude oil theft and pipeline vandalism in the Niger Delta region, promote non-oil exports, encourage local production to reduce import dependence and create a more conducive environment for foreign direct investments.
They also urged the CBN to remain consistent with its reform agenda, deepen transparency and efficiency in the foreign exchange market, introduce more attractive incentives for Nigerians in the diaspora to send money home through official banking channels, and pursue policies that will attract stable, long-term investments capable of supporting reserves growth and ensuring lasting stability of the naira.